Global smartphone shipments declined 22.0% year-on-year (YoY) to 255.3 million units in the third quarter of 2026 (Q3 2026), marking the largest YoY decline recorded in any quarter, according to preliminary data from the IDC Worldwide Quarterly Mobile Phone Tracker. The AI-led memory crisis continues to disrupt the market, with component costs rising to unprecedented levels and supply coming under pressure.
IDC expects market growth to remain constrained through 2027, with a possible recovery pushed to 2028 at the earliest. The research firm said original equipment manufacturers (OEMs) are increasingly recognizing a permanent structural shift in industry cost dynamics. While the disruption presents challenges, it also creates opportunities for vendors to gain market share.
IDC said strategic execution and innovation will be increasingly important, with manufacturers that adapt their product, pricing and demand-generation strategies to higher costs better positioned to gain share.
Francisco Jeronimo, vice president for Worldwide Devices at IDC, said,
The third quarter shows the full impact and damage of the memory crisis.
He noted that pressure is shifting from vendors to consumers as higher prices reach retail shelves, prompting many buyers to keep their current devices longer. Chinese brands face particular challenges because of their exposure to low-end smartphones, forcing them to choose between protecting margins and defending shipment volumes as demand weakens.
Jeronimo expects volumes to remain under pressure in the coming quarters, while vendors with “scale, secure supply and a premium mix” continue to gain share in a smaller market.
Global Smartphone Shipments by Vendor in Q3 2026
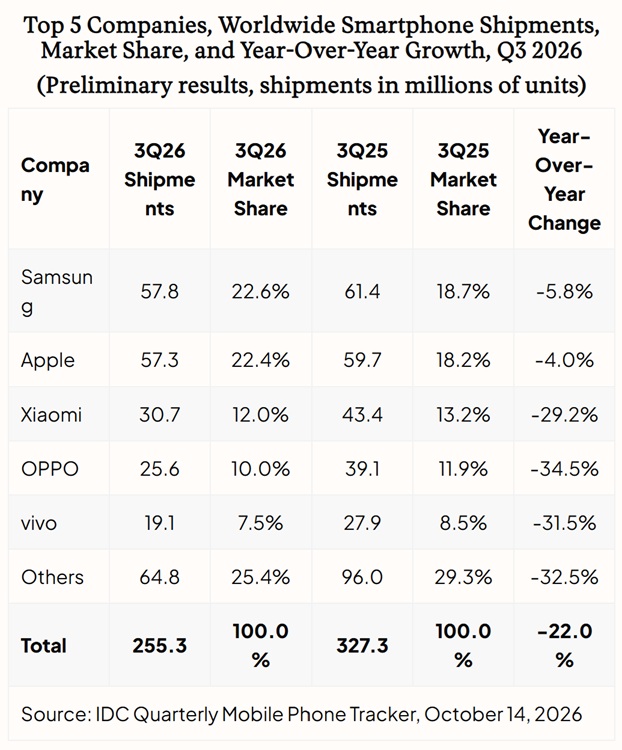
Vendor rankings remained broadly similar to the previous quarter. Samsung and Apple continued to gain market share, while shipment declines intensified for Xiaomi, OPPO and vivo. IDC reported the following shipment volumes and market shares:
- Samsung: 57.8 million units, 22.6% market share
- Apple: 57.3 million units, 22.4% market share
- Xiaomi: 30.7 million units, 12.0% market share
- OPPO: 25.6 million units, 10.0% market share
- vivo: 19.1 million units, 7.5% market share
- Others: 64.8 million units, 25.4% market share
- Total: 255.3 million units, 100.0% market share
Kiranjeet Kaur, associate research director for Worldwide Devices at IDC, said,
While vendor ranking remains similar to last quarter, Samsung and Apple continue to gain share as players like Xiaomi, OPPO, vivo shipment declines intensify.
She added that consumers who cannot postpone a purchase may find better value during the holiday quarter, when promotions and discounts are expected to be at their most attractive, rather than waiting for prices to ease.
Despite sluggish sales, some vendors have raised production plans ahead of an expected tightening in component supply next year. Kaur warned that if demand remains weak, this could lead to “inventory build-up heading into 2027,” adding further downside risk to IDC’s 2027 forecast.
Memory Crisis Puts Pressure on Smartphone Market
Nabila Popal, senior research director for Worldwide Devices at IDC, said the sharp downturn the industry had anticipated materialized in Q3 2026, with shipments declining a record 22% YoY. She warned that “the worst is yet to come” and said current indicators suggest the market has not yet reached the bottom.
IDC reported that memory costs have surged approximately 350% since last year and continue to rise, putting substantial pressure on vendor margins and smartphone shipments. The research firm noted that while memory inflation is beginning to slow, the sequential increase in Q3 eased to the low double digits, compared with roughly 50%–100% in previous quarters. However, costs remain elevated across other critical components, further adding to the pressure on manufacturers.