Global smartphone shipments declined 20% year-on-year (YoY) in Q3 2026, reaching their lowest third-quarter level since 2012, according to preliminary estimates from Counterpoint Research’s Market Monitor service. The decline was close to Counterpoint’s expectations as rising DRAM and NAND prices intensified the memory cost shock during the quarter.
Global smartphone shipments Q3 2026
Higher memory prices increased bill of materials (BOM) costs and worsened component shortages, disrupting shipments across the industry. Smartphone manufacturers passed on these costs to consumers, driving up global smartphone retail prices by 20% so far in 2026 and increasing average selling prices (ASPs). These pressures affected manufacturers differently, depending on their product portfolios, pricing decisions and component supply.
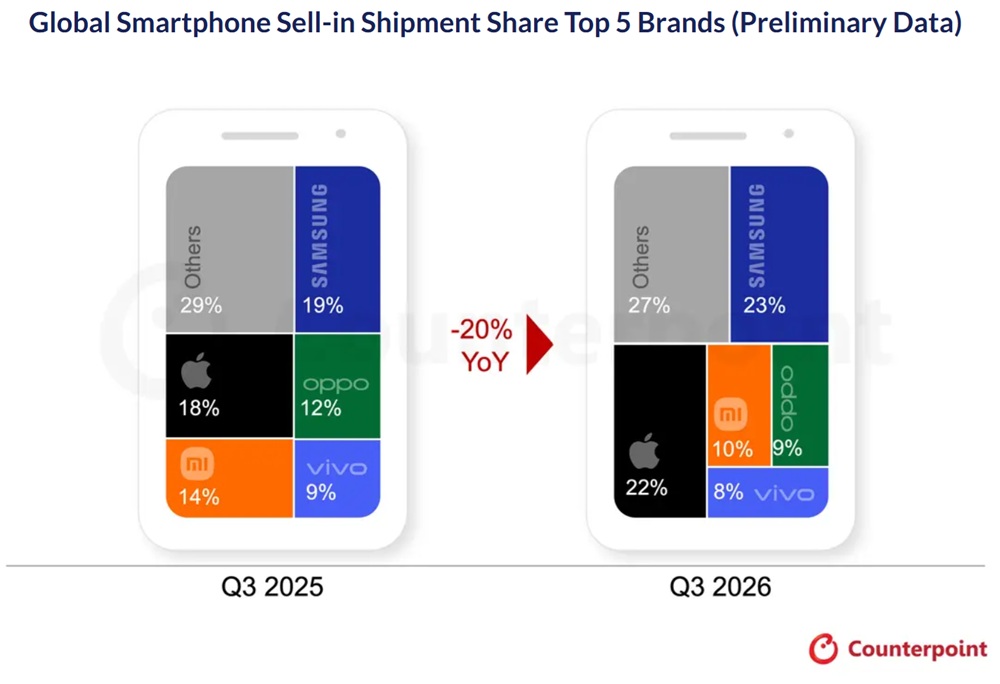
Samsung retained the top position with a 23% market share, followed by Apple at 22%. Both recorded smaller shipment declines than Xiaomi, OPPO and vivo, although their results were shaped by different product and pricing strategies.
Samsung
Shipments declined 3% YoY, while market share rose to 23%, the largest gain among major manufacturers. Its focus on higher ASPs and revenue growth supported value growth despite lower shipment volumes. Premiumization and its foldable launch contributed to its product mix, with the Galaxy Z Fold8 series recording strong initial demand. Stable component supply also supported the mid-range Galaxy A series in emerging markets as some Chinese brands reduced their presence.
Apple
Shipments declined YoY, although market share reached 22%, crossing 20% for the first time in any Q3. The absence of a base iPhone 18 resulted in a smaller launch-month channel fill than the full iPhone 17 lineup a year earlier.
Apple also raised prices, although the impact was limited to the final weeks of the quarter. However, the iPhone 18 Pro models recorded a stronger launch than their predecessors, particularly in China and India, while sustained demand for the iPhone 17 series helped offset the shipment decline.
Xiaomi
Shipments fell more than 30% YoY, reducing market share to 10%. The company reduced its exposure to lower-price segments and non-core overseas markets, raised ASPs and tightened shipment plans to avoid selling devices at uneconomical margins.
In China, the Xiaomi 18 series and foldable models received a positive response in the upper mid-range and premium segments. Its in-house XRING O3 chipset also supported differentiation in the premium segment.
OPPO and vivo
Both brands recorded shipment declines of more than 20% YoY, with market shares falling to 9% and 8%, respectively. Both raised prices across their entry-level and mid-range portfolios in response to higher memory costs. OPPO consolidated its portfolio and operations across OPPO, realme and OnePlus to reduce overlap and improve cost efficiency, while shifting supply from thinner-margin segments towards higher-return markets and models.
Meanwhile, vivo prioritised India and China, strengthening its Y series for value-conscious consumers while expanding its X, V and S series. Price increases pushed budget models out of key price bands, while stock shortages further constrained vivo’s shipments.
Outlook
Counterpoint Research expects market conditions to remain challenging for the rest of 2026, as elevated component costs and weaker affordability continue to affect the smartphone market. OEMs are likely to prioritise profitability over shipment volumes through the following measures:
- Production cuts: Manufacturers are likely to reduce production to manage costs and supply constraints.
- Tighter portfolios: OEMs are expected to streamline their product lineups and focus on fewer models.
- Focus on premium devices: Manufacturers are likely to prioritise higher-priced devices over lower-margin segments.
Meanwhile, price-sensitive segments are expected to face further pressure from higher device prices and limited component availability. A meaningful recovery in overall smartphone shipment volumes is unlikely until component costs and supply conditions improve.
Commenting on the global smartphone market, Senior Analyst Shilpi Jain said,
Q3 was the second consecutive quarter to take the full brunt of the memory crisis. The extreme memory shortage is pushing the smartphone market into a more selective phase, reshaping OEM strategies and even consumer behaviour. Consumers are holding on to their devices longer than estimated, increasingly considering refurbished devices and prioritising higher-value devices, while OEMs are adjusting portfolios, pricing, and market strategies to protect profitability. This is creating greater pressure across the mass market, while premium demand remains comparatively resilient, widening the gap between premium and price-sensitive segments.